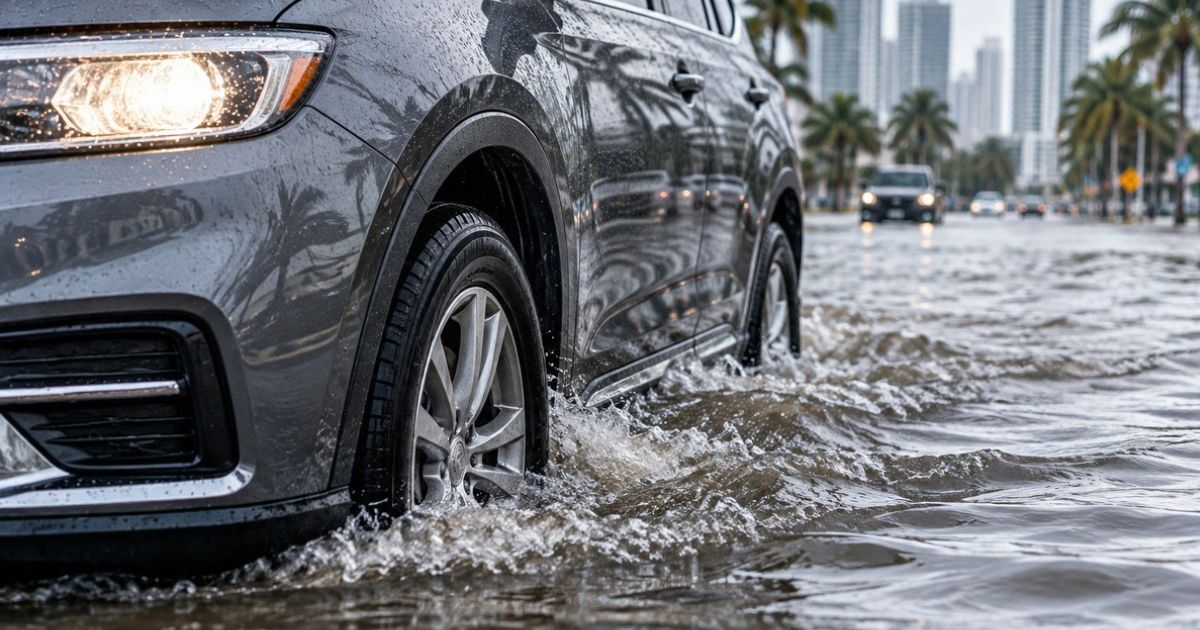
Flooding caused by heavy rains or extraordinary tides in Florida can result in serious damage to vehicles, but having insurance does not guarantee that the company will cover the repairs, as it all depends on the coverage purchased and the terms of the policy.
The Florida Department of Financial Services explains that the coverage known as comprehensive or other than collision (comprehensive coverage or coverage for damages other than a collision) generally protects the vehicle against damage caused by floods, as well as other incidents such as fires, theft, vandalism, and storms.
This coverage is different from liability insurance, which protects against certain damages inflicted on other people or their property, but is not designed to cover the repairs of the insured's own vehicle due to a flood.
In other words, a driver who only has the mandatory minimum coverages in Florida might find that their insurance does not cover damage caused by water to their own vehicle.
The distinction becomes important in the midst of the coastal flooding affecting southern Florida due to the extraordinary tides of October.
This Wednesday, the National Weather Service (NWS) has issued a coastal flood warning for the coastal areas of Miami-Dade, Broward, and Palm Beach until 8:00 p.m. Eastern Time.
The agency warns that numerous roads may remain closed and that water could reach homes, businesses, and infrastructure located in low-lying areas. After that time, a notice for moderate coastal flooding is expected to continue until Thursday night.
The threat is not just a prediction. The extraordinary tides have already caused flooding and street closures in Miami Beach and Fort Lauderdale, where authorities also had to respond to emergencies.
For car owners, the main recommendation is to check if their policy includes comprehensive coverage, which is typically purchased as an add-on.
What happens if the vehicle was parked and the water reached it?
If the owner has comprehensive coverage, flood damages may be covered, but the insurer must assess the circumstances and determine if payment is warranted according to the contract.
The coverage may include damage to mechanical, electrical components, and other parts of the vehicle, depending on the specific terms of the policy.
However, not all companies use identical contracts. The Florida Department of Financial Services warns that some policies offer broader protections than others, so it is essential to review their limits and exclusions.
It is also important to check the deductible, that is, the amount the owner must pay out of pocket before the insurance company covers the covered expenses.
For example, if a covered repair costs $4,000 and the policy sets a deductible of $500, the insured would have to cover the first $500, and the company could pay the remaining $3,500, provided the claim is accepted and there are no other applicable limits.
To determine the severity of the damage, factors such as the height reached by the water, the affected areas, and the cost of repairs must be examined.
A car can sustain significant damage even if the water hasn't completely submerged the body, especially when it reaches electrical or electronic components.
If water has entered the vehicle, the safest course of action is not to try to start it. Attempting to operate a flood-affected engine can worsen the damage, especially in the case of salt water.
The owner should wait until it is safe to approach the car and ensure that a professional evaluates its condition before using it again.
It's also advisable to take photographs of the exterior, interior, the license plate, and the affected areas, as well as document how far the water reached.
If there is a visible mark of moisture or sediment, it is advisable to photograph it, as it can help illustrate the extent of the flooding.
The next step is to contact the insurer to report the incident and understand the claims procedure.
The official Florida guide for claims after disasters recommends reporting damages as soon as possible, keeping photographs and receipts, and avoiding discarding affected items before they can be inspected, as long as it is safe to keep them.
The driver should also consult with their company before authorizing major repairs or moving the vehicle, especially if a tow truck is needed.
Some policies include towing assistance or reimbursement for renting another car, but those benefits are not guaranteed just by having flood coverage.
Another important difference is that collision insurance, designed primarily to cover damages from collisions, does not automatically replace comprehensive coverage.
The Department of Financial Services also reminds that business expressions such as full coverage, often used to describe comprehensive insurance, do not alone indicate which risks are covered.
The only way to confirm it is to check the contract and directly verify with the company what the current policy includes.
What to do if the insurer rejects the claim?
The state authority explains that companies must communicate denial decisions in writing. If the insured has additional evidence that contradicts the evaluation, they can submit it to request a review.
You can also request assistance from the Florida Department of Financial Services, which provides guidance to consumers regarding issues with insurers and has mechanisms in place to help resolve certain disputes.
In October, Florida opened a special assistance center for individuals who needed to file claims after Hurricane Isaias, as part of the measures to facilitate support for policyholders affected by disasters.
Most recently, the state attorney's office announced an investigation into possible restrictions imposed by some insurers on homeowners who hire public adjusters to claim damages to their homes.
These records mainly pertain to property insurance and do not alter the terms of automobile policies, but they highlight the importance of understanding the rights of policyholders before filing a claim.
Related videos:
Filed under: